
Home Insurance
From military service to legal service
Insured for What It's Really Worth
Coverage That Matches What Your Home Is Actually Worth
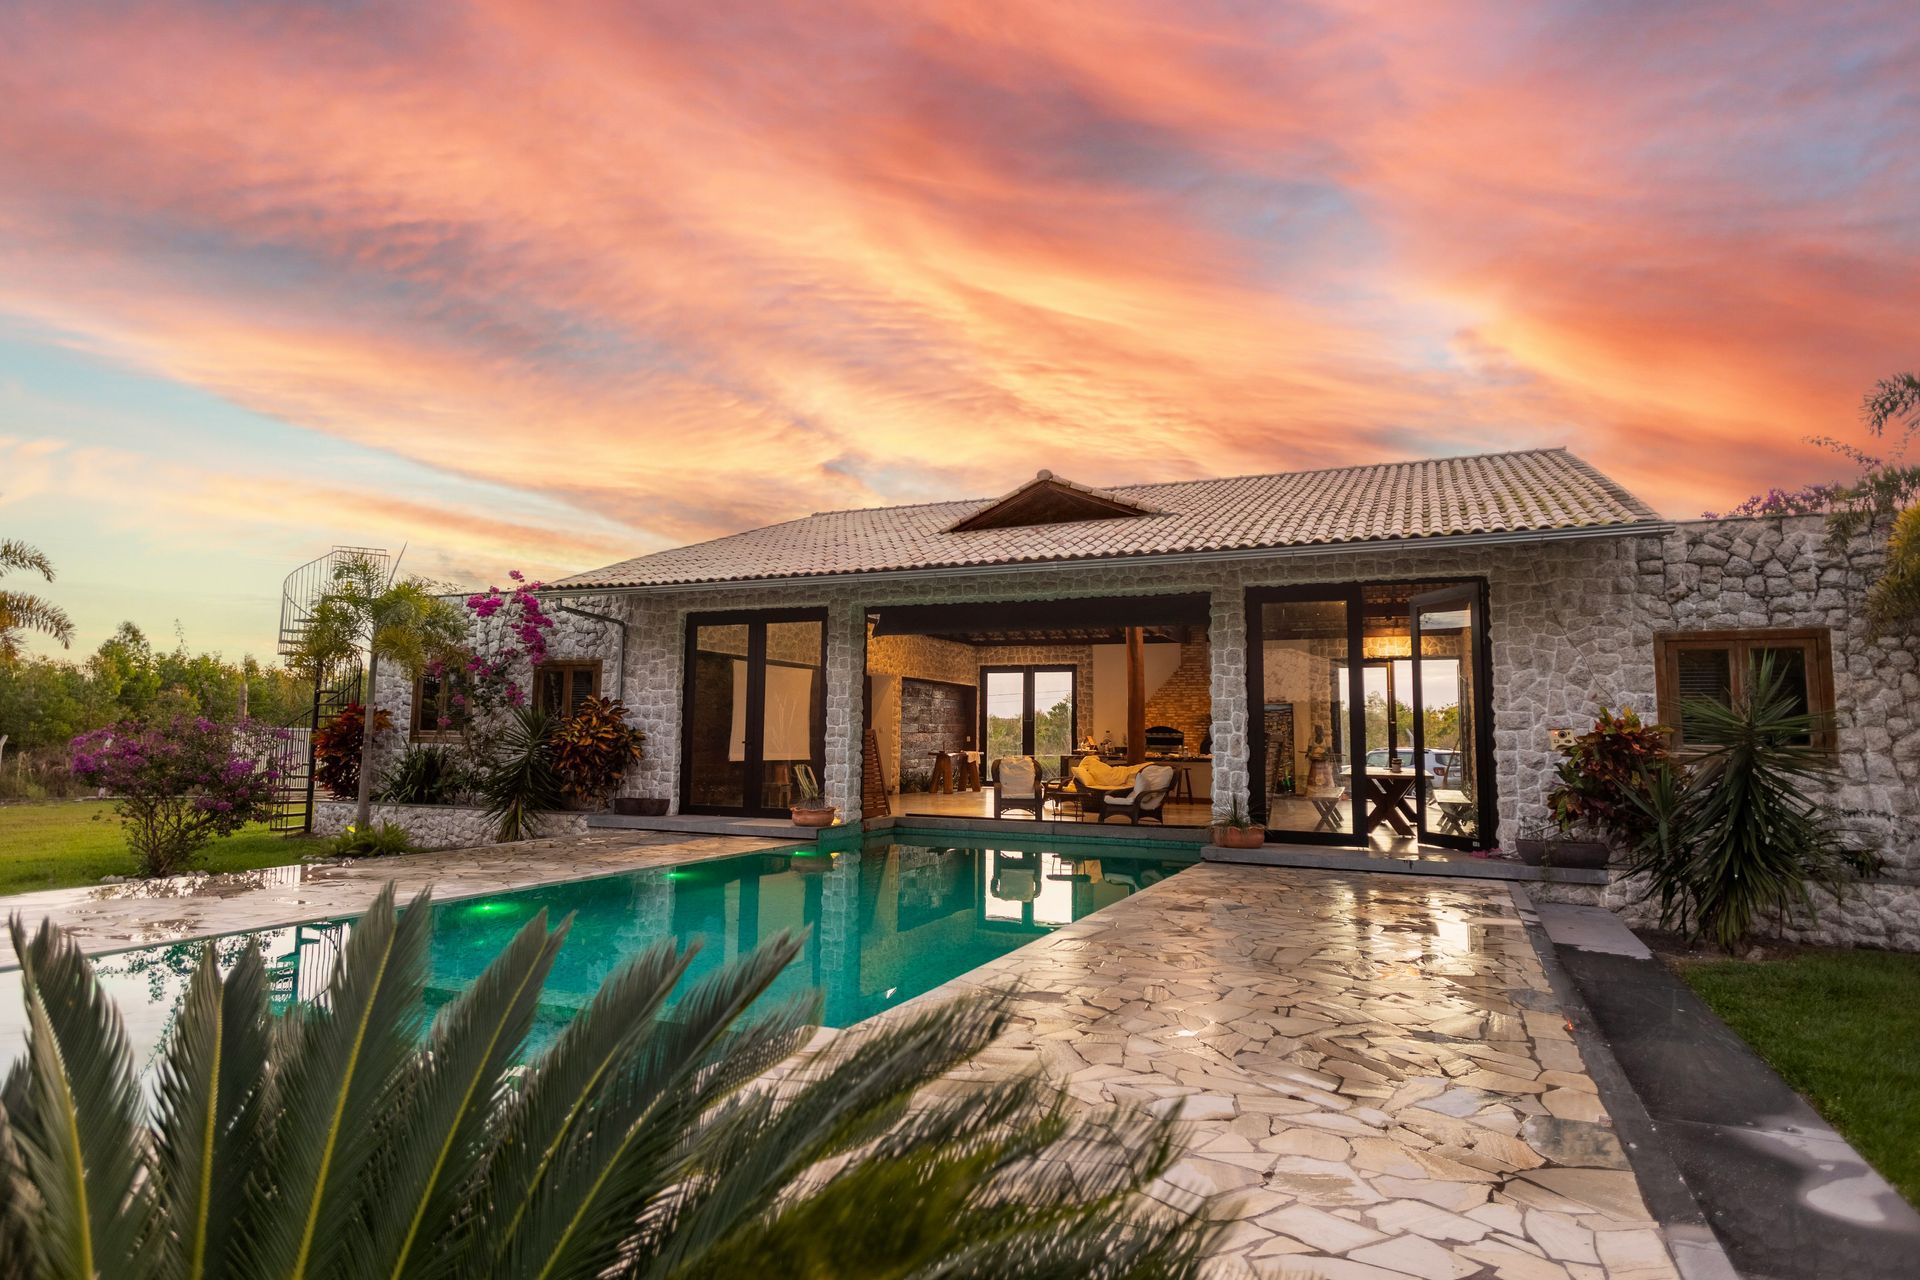
A standard homeowner's policy is built around averages. If your home was custom built, extensively renovated, or sits on rural or farmland acreage, that average is often wrong, and it's usually wrong on the low side. We start by identifying your home's true replacement cost, not its market value, so your coverage reflects what it would actually take to rebuild.
Replacement cost and market value aren't the same number. Market value reflects what a buyer would pay today, land included. Replacement cost reflects the actual cost to rebuild the structure itself, materials, labor, custom finishes, and all. A home can be underinsured by a significant margin when a policy is based on the wrong one.
Every Property You Own, Under One Roof
Primary residence, vacation home, or a working farm property, each carries its own exposure and its own gaps if handled in isolation. We evaluate your properties together as part of one household risk profile, so coverage stays consistent no matter how many homes you own or how often you're between them.
- Primary residences, including custom-built and extensively renovated homes
- Vacation and second homes, covered even when unoccupied for extended periods
- Multi-property portfolios, evaluated together rather than policy by policy
- Farmland and rural properties, including outbuildings and acreage-specific exposures
- Coastal and severe weather exposure across Alabama, Texas, Florida, and Georgia
Fewer Surprises When it Matters Most
A claim is the worst time to discover a gap. Our risk assessment looks at your property's specific exposures, construction, location, weather risk, and secondary use, before coverage is placed, so what's covered actually matches what could go wrong.
Ready to Have This Handled for You?
Many homeowners reach this point after researching deductibles, hail coverage, and policy language online. The next step is having this reviewed by a local team that handles Cheyenne homeowners insurance every day and can compare options clearly.
Your Questions, Answered Clearly
Do I need special coverage for a home worth over a million dollars?
Likely, yes. Standard policies often cap coverage or use replacement cost estimates that don't reflect a high-value or custom-built home's true rebuild cost. High value home insurance is built on an actual valuation of your property, not a generic estimate.
Do I need special coverage for a vacation home?
Yes. Vacation homes carry different risks than a primary residence, including extended vacancy and, in many cases, coastal or weather exposure. We evaluate vacation homes as part of your overall property risk profile rather than as an afterthought.
What's the difference between replacement cost and market value for home insurance?
Market value reflects what a buyer would pay, including the land. Replacement cost reflects what it would actually cost to rebuild the structure. Home insurance should be based on replacement cost, since that's the number that determines whether you're properly covered after a loss.
Does home insurance cover farmland or rural properties?
Yes. Farmland and rural properties come with exposures, outbuildings, acreage, and distance from emergency services, that standard suburban policies don't account for. We factor these in during the risk assessment before recommending coverage.
